Jenna’s Bottom Line
AI infrastructure spending creates a useful place to look for businesses with growing demand. It does not create a guaranteed return for their shareholders. This October watchlist separates reported results, management forecasts and investment judgment, then asks the less glamorous question: how much success is already in the price?
Key Takeaways
- Hyperscaler spending plans are large, but accounting definitions and reporting periods differ. Total corporate capital expenditure is not an audited total of AI-only spending or guaranteed revenue for this watchlist.
- AI stocks fall into two broad categories: platform plays (software companies driving AI adoption) and infrastructure picks and shovels (hardware and networking companies powering the physical build-out).
- A useful AI watchlist starts with disclosed revenue, an explainable competitive advantage and evidence of capital discipline. Those are research tests, not proof that any stock is a bargain.
- Valuation still matters. Test the price against slower growth, lower margins and dilution, not only management’s preferred outcome.
- This hub covers Nvidia, Broadcom, Vertiv, and Nebius in dedicated spoke articles. Our existing Hub 1 coverage addresses Palantir, Arista Networks, and Datadog separately.
The Spending Case, With the Accounting Left In
I have covered enough technology investment cycles to know what speculative excess looks like. Large profitable customers and measurable supplier revenue make the present cycle worth studying. They do not eliminate overbuilding, poor returns on capital or speculative pricing.
The accounting matters before anyone reaches for a calculator. In its July 29 earnings call, Microsoft put calendar-2026 capex at approximately $175 billion after a lease-classification change; it said underlying investment expectations were unchanged. Meta’s July 29 results gave 2026 capex guidance of $130 billion–$145 billion, including finance-lease principal payments. These are company forecasts on different measurement bases, not a clean AI-only total.
Demand is also visible in reported sales. Alphabet’s July 22 Q2 release reported Google Cloud revenue of $24.8 billion, up 82% year over year. Cloud revenue includes more than AI, just as a technology company’s capex includes more than checks written to the stocks in this article.
The investment thesis is that sustained demand can support selected suppliers. The countercase is that customers overspend, shift work to their own chips, negotiate lower prices or delay projects. There is no guaranteed demand floor. A capex plan can be revised; a supplier can lose share; a strong industry can still contain an expensive stock.
The Two Categories of AI Stocks
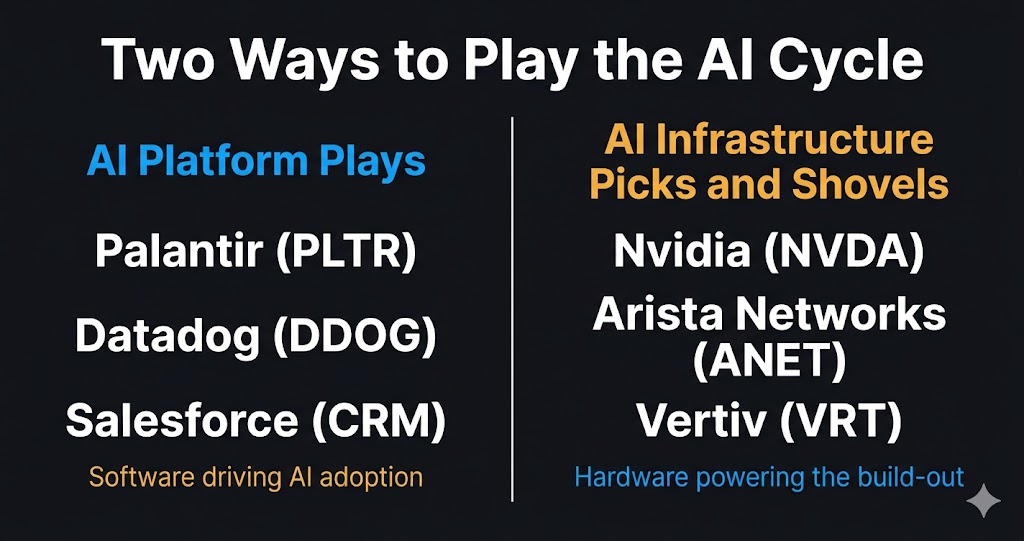
Before buying any AI stock I want to know which category it sits in. They have different risk profiles, different valuation frameworks, and different relationships to the underlying capital expenditure cycle.
AI platform plays are software companies whose products are driven by or integrated into AI adoption. Palantir Technologies (PLTR) and Datadog (DDOG) fall into this category. Their products can benefit as enterprises adopt AI tooling, analytics and infrastructure monitoring, but neither company reports all revenue as AI revenue. Evaluate switching costs rather than assuming them. Revenue growth, retention, GAAP profitability and consistently defined Rule of 40 measures all belong in the analysis.
AI infrastructure picks and shovels are hardware and networking companies supplying the physical layer of the AI build-out. Nvidia (NVDA), Arista Networks (ANET), Vertiv (VRT), and Broadcom (AVGO) fall here. They supply different parts of data centers, GPU clusters and networking. Proprietary technology, qualification cycles and switching costs may help defend a supplier, but customer concentration and competing architectures can offset those advantages. Compare earnings and cash flow with capital requirements, not only sales growth.
The distinction is a starting point, not a trading rule. Hardware stocks do not reliably protect capital in every risk-off market, and software does not automatically outperform in every recovery. A hardware company with a stretched valuation can fall just as hard as a software company. Surprise, the market reads the price tag too.
How to Evaluate an AI Stock
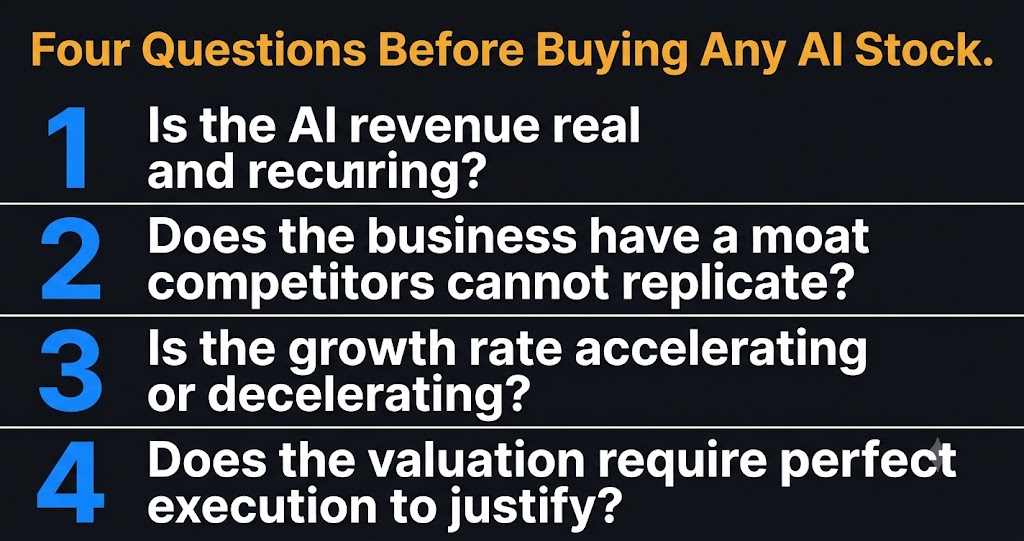 The AI label has been attached to enough mediocre businesses at this point that it requires active skepticism, not automatic enthusiasm. I run four questions on every AI stock before forming a view.
First: what does the company actually disclose? Palantir reports commercial and government revenue; it does not separately break out AIP revenue in its Q2 results. NVIDIA’s Data Center category and Arista’s management-defined AI targets also have different scopes. Do not relabel all three as identical, recurring AI revenue streams. “We are well positioned for AI” is not a segment disclosure.
Second: can customers replace the product without a large cost, delay or performance penalty? CUDA and Arista’s EOS are relevant software ecosystems, but neither makes displacement impossible. Look for evidence in deployments, customer retention and margins. Hardware without a proprietary software stack can still have manufacturing know-how, intellectual property or qualification barriers; “no software” does not automatically mean “commodity.”
Third: is the growth rate accelerating or decelerating? Accelerating revenue growth with expanding margins is the signal I want. Decelerating growth with a high multiple is the setup for a painful repricing regardless of how good the AI narrative sounds.
Fourth: does the valuation require perfect execution to justify? A stock priced for five years of flawless execution has no margin for the inevitable quarterly disappointment. I want to own AI businesses where the valuation leaves some room for error, even if that means accepting a lower starting yield on the thesis.
What I Look for in AI Stock Earnings Reports
Earnings calls for AI infrastructure companies contain more signal per minute than almost any other category of business. I listen for four things specifically.
- Backlog and remaining performance obligations. Backlog and RPO help assess visibility, but timing, cancellation terms and customer concentration matter. Microsoft’s July 29 call gave commercial RPO a weighted-average duration of 2.3 years and expected roughly 30% to become revenue in the next 12 months. Do not impose one 12–24-month recognition window on every company.
- Gross margin trajectory. Check mix, supply costs and product-transition expenses alongside pricing power. Growth can coincide with margin compression, and adjusted margins should not be substituted for GAAP margins without explanation.
- Capital expenditure guidance from hyperscaler customers. I track hyperscaler capex announcements as one demand indicator, then check supplier orders, delivery schedules and customer concentration. Spending can go to land, buildings, internal development or competing suppliers; an announced increase does not flow proportionately to every stock here.
- Management commentary on demand visibility. Executives who can speak to specific customer commitments and contracted revenue rather than vague demand trends are operating businesses with genuine visibility. Specific contract disclosure is more informative than general enthusiasm, but the terms, timing and credit quality still need inspection.
Experience Transparency
I started building positions in AI infrastructure names in early 2023 when the consensus view was that the post-ChatGPT enthusiasm was another dot-com bubble in formation. What changed my thinking was not the hype. It was the capex commitments. When Microsoft, Alphabet, Meta, and Amazon started guiding for tens of billions in quarterly infrastructure spending with specific contractor relationships and data center timelines attached, I stopped treating it as speculation. Contracted infrastructure spending is not a narrative. It is an order book. The companies in the direct path of that order book became some of the strongest positions in my portfolio over the following two years. I hold PLTR. I watch the rest closely and update these analyses every earnings cycle.
The AI Stocks Covered in This Hub
This hub follows four different ways to study AI demand. Each has a dedicated article covering the business, reported results and valuation risks. Inclusion is not a ranking or a claim that investors who missed an earlier rally should buy now.
- Nvidia (NVDA). A major GPU supplier for AI training and inference. Data center revenue has grown from a secondary business segment to the primary driver of the company’s earnings trajectory. See our full analysis: Nvidia stock analysis.
- Broadcom (AVGO). A semiconductor and infrastructure software company with deep hyperscaler relationships and a growing custom AI chip business alongside its networking and storage franchise. See our full analysis: Broadcom stock analysis.
- Vertiv (VRT). A provider of power and cooling infrastructure for data centers. Higher GPU density can increase thermal-management and power-delivery demands; efficiency improvements and competing designs can change the economics. See our full analysis: Vertiv stock analysis.
- Nebius (NBIS). A specialized AI-cloud provider with substantial capacity-building and financing requirements. Its partnerships and customer commitments need to be considered alongside deployment, utilization and balance-sheet risks. See our full analysis: Nebius stock analysis.
Our existing Hub 1 coverage addresses the AI infrastructure software and networking layer in depth. For full analysis of Palantir Technologies (PLTR), Arista Networks (ANET), and Datadog (DDOG), see our AI infrastructure stocks hub.
The Risk Case for AI Stocks in 2026
I want to be direct about the risks because ignoring them is not analysis. It is cheerleading.
The primary risk is that hyperscaler capex commitments do not translate into the revenue growth that current valuations assume. If Microsoft, Alphabet, Meta, and Amazon pull back on AI infrastructure spending due to ROI concerns, the downstream impact on Nvidia, Arista, and Vertiv could be material, with timing depending on contracts, customer decisions and delivery schedules.
The secondary risk is valuation. A business can grow while its stock falls if results do not meet expectations embedded in the price. Use a range of outcomes and consider how much of your portfolio already depends on the same spending cycle. No fixed percentage predicts how far a disappointment will move a stock.
The third risk is competition. AMD accelerators and customers’ own silicon, including Google TPUs and Amazon Trainium, give buyers alternatives for some workloads. Arista competes with other networking vendors as well as NVIDIA’s networking products. The speed and economics of substitution vary; they cannot be inferred from one benchmark or product announcement.
For a look at a paid research service, see our Jim Rickards’ Strategic Intelligence review. A newsletter is an optional research input, not independent validation of this watchlist or a substitute for company filings.
How to Research AI Exposure Responsibly
Suitability depends on your financial situation, time horizon, liquidity needs and existing exposures. Conviction alone is not a risk-management plan.
- If you are new to the theme. Compare the business models in our Nvidia, Broadcom, Vertiv and Nebius analyses before deciding whether any individual stock belongs in your portfolio. Size and popularity do not establish suitability.
- If you already own the obvious names. The AI infrastructure spoke articles in this hub are designed to help you evaluate whether adding the less obvious names adds genuine diversification or just AI concentration at a different price point.
- If you are concerned about valuation. Spreading purchases over time changes entry-timing risk, but does not make an overvalued business cheap or prevent losses. See our guide to dollar cost averaging for the framework.
- If you want research support. Our Louis Navellier’s Growth Investor review discusses the service. Check current pricing, terms and substantiated performance evidence before subscribing; marketing claims about early picks are not a substitute for a verifiable track record.
Wall Street Reality Check
Big spending plans support a research thesis, not a conclusion about where we are in the stock-market cycle. Suppliers may become larger businesses and still deliver disappointing shareholder returns if buyers pay too much or dilution absorbs the gains. Test the optimistic case against slower growth and lower margins. The spreadsheet should have a bear case, not just a prettier font.
Bottom Line
The useful question is which businesses can convert demand into durable per-share cash flow at a price that leaves room for error. Start with company disclosures, keep forecasts separate from results and compare alternatives. This watchlist is a place to begin the research, not permission to skip it.
Further Reading
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice. StockHitter.com and Jenna Lofton are not registered investment advisors. All investing involves risk, including the potential loss of principal. Past performance does not guarantee future results. Always conduct your own due diligence and consult a licensed financial professional before making investment decisions. Jenna Lofton holds a position in PLTR. Some links on this page may be affiliate links, meaning StockHitter.com may receive compensation if you subscribe to a service at no additional cost to you. This does not influence our editorial opinions.