By Jenna Lofton, StockHitter.com
Jenna’s Bottom Line
Every GPU that runs an AI workload generates heat. Every AI data center needs power before a single chip can operate. Vertiv sits at the intersection of both problems. Its latest reported quarter, Q2, brought stronger adjusted earnings and a second consecutive increase in full-year guidance. Since then, proposed acquisitions have expanded the strategic story and the potential cash commitments. The next checkpoint is the October 28 Q3 report. There is plenty to like here, but power and cooling do not make a stock immune to valuation risk.
Key Takeaways
- Vertiv reported Q2 2026 net sales of $3.274 billion on July 29, up 24 percent year over year. GAAP diluted EPS was $1.27; adjusted diluted EPS was $1.52, up 60 percent. Adjusted operating margin reached 22.6 percent.
- Management attributed Q2 revenue timing shifts to supply chain congestion and multi-phased project execution. That is management’s explanation, not proof of a single cause for the share-price reaction. Q3 results are scheduled for October 28, 2026 and had not been reported as of this update.
- Vertiv raised full-year 2026 guidance for the second consecutive quarter. Net sales guidance moved to $13.8 to $14.2 billion, up from $13.5 to $14.0 billion after Q1. Adjusted diluted EPS guidance moved to $6.65 to $6.75, up from $6.30 to $6.40.
- Operating cash flow hit $1.1 billion in Q2, up 241 percent year over year. Adjusted free cash flow reached $925 million, up 234 percent. The company ended the quarter with $5.6 billion in liquidity and a net cash position.
- The 2026 fact sheet puts data centers at approximately 85 percent of FY2025 revenue, with communications at 10 percent and commercial/industrial markets at 5 percent. These are rounded historical mix figures, not Q2 segment results.
- The September UIG and KES announcements are acquisition agreements, not completed deals. UIG calls for about $1.45 billion in cash at closing plus up to $1.15 billion in contingent cash consideration. Integration, closing conditions, and financing deserve attention alongside the growth story.
What Vertiv Actually Does
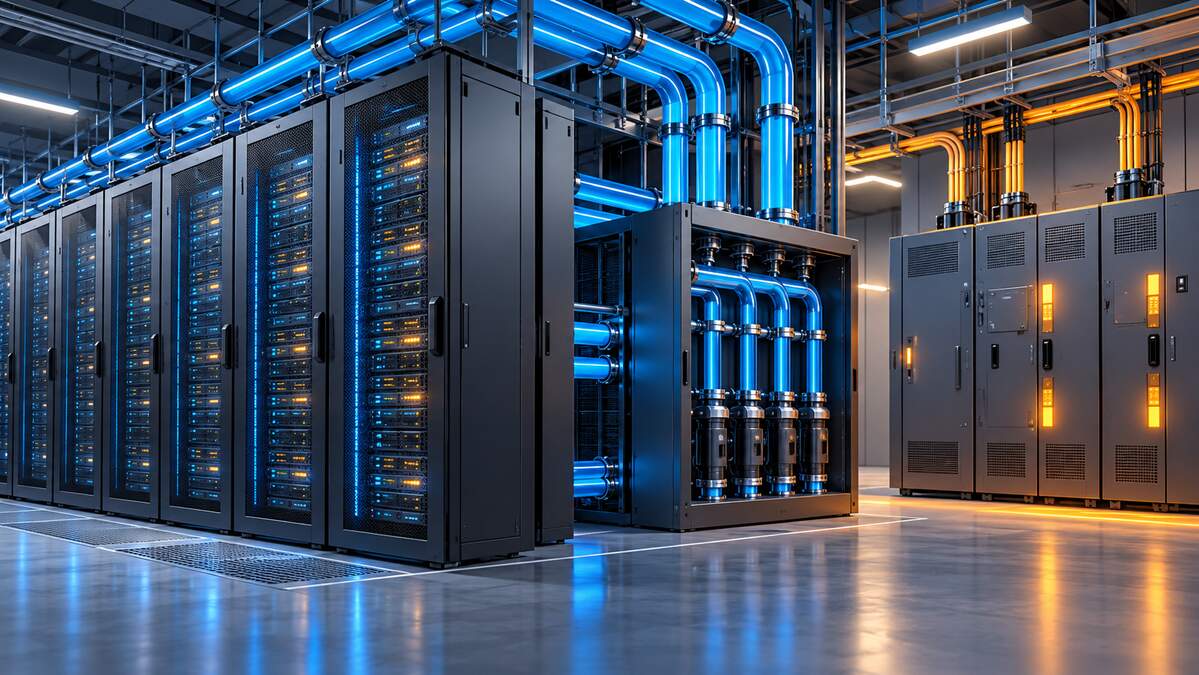
Vertiv designs and manufactures the physical infrastructure that keeps data centers running. That includes uninterruptible power supplies, switchgear, busways, racks, chillers, computer-room air handlers, and liquid cooling distribution units.
The company is not a chip business. It sits between the utility grid and the server racks. Power and cooling have to be ready for GPUs to operate reliably, although not every data center uses Vertiv equipment. Its opportunity comes from supplying those essential systems, not from an exclusive claim on every AI build-out.
According to Vertiv’s 2026 company fact sheet, approximately 85 percent of FY2025 revenue came from data centers, 10 percent from communications networks, and 5 percent from commercial and industrial markets. The company rounds these market shares to the nearest 5 percent. That exposure makes Vertiv relevant to data-center spending without making it a semiconductor designer or making every data-center sale AI-related.
Vertiv’s Q2 2026 Results: The Numbers
Vertiv’s July 29 Q2 release remains the latest reported financial baseline for this update. Net sales were $3.274 billion, up 24 percent from Q2 2025: approximately 18 percentage points from organic growth, 5 from acquisitions, and 1 from currency. These are growth contributions, not shares of total revenue.
Management described minor revenue timing shifts from temporary supply-chain congestion and multi-phased project execution. It also described strong demand and raised the annual outlook. That supports a timing explanation, but investors still need subsequent results to show that delayed work converts into sales. A reassuring explanation is useful; collecting the revenue is better.
Adjusted diluted EPS was $1.52, up 60 percent year over year. GAAP diluted EPS grew 53 percent to $1.27. GAAP operating profit rose 44 percent to $638 million, while adjusted operating profit increased 51 percent to $738 million. The 22.6 percent adjusted operating margin was up 410 basis points from Q2 2025. Those adjusted measures are non-GAAP and should be read with the company’s reconciliation.
Operating cash flow was $1.1 billion and adjusted free cash flow was $925 million in Q2, up 241 percent and 234 percent, respectively. June 30 liquidity was $5.6 billion and the company reported net cash. Those are quarter-end snapshots. They are not a promise that liquidity stays unchanged after new acquisitions, and adjusted free cash flow does not deduct acquisition purchase prices.
Why Liquid Cooling Is the Growth Engine
Traditional lower-density data centers often use air cooling. There is no single standard rack power level: density varies with the servers, workload, and facility design. Comparing actual system specifications is more useful than assigning every conventional or AI rack one fixed power number.
High-density accelerator systems can require liquid cooling to move heat away from chips efficiently. Direct-to-chip systems circulate coolant through cold plates rather than relying only on room air. The exact mix of liquid and air cooling depends on the equipment and architecture, so “AI data center” is not one universal cooling specification.
Vertiv’s liquid-cooling investment helps explain its place in the AI infrastructure story. Q2 showed company-wide operating leverage, with adjusted operating profit growing faster than sales. It does not, by itself, disclose the standalone margin or growth contribution of liquid cooling. Keep the attractive product thesis separate from financial detail the company has not reported.
Experience Transparency
I started researching Vertiv seriously in late 2024 after spending time with an enterprise infrastructure engineer who was managing a hyperscale data center expansion. His exact words were: “We cannot deploy the GPUs until Vertiv’s cooling equipment is installed. The chips are arriving before the infrastructure is ready.” That delivery sequence told me everything I needed to know about Vertiv’s position in the AI build-out. The chips get the headlines. The power and cooling get the purchase orders. I began building a position shortly after that conversation, and the pattern from the Q2 report, management-described revenue timing shifts paired with adjusted margin expansion and a raised full-year guide, is exactly the kind of noise that shakes out short-term traders while leaving the underlying thesis intact.
The Acquisition Strategy: Building the Full Thermal Chain

By the July 29 Q2 report, Vertiv had completed the three 2026 acquisitions discussed below. Each added a different capability for high-density infrastructure. The September agreements described afterward are a separate category: proposed transactions still subject to closing.
In April 2026, Vertiv acquired BMarko Structures, a U.S.-based provider of custom-engineered structural fabrication. The acquisition strengthens in-house structural fabrication and engineering control for manufactured and converged infrastructure solutions. As AI data center deployments accelerate, the ability to deliver custom-built infrastructure faster is a competitive differentiator.
Also in April 2026, Vertiv acquired Strategic Thermal Labs, a specialist in advanced liquid cooling technologies. The acquisition adds cold-plate design, server-side liquid-cooling engineering, and high-density thermal validation capability. These are useful tools for serving increasingly demanding accelerator systems, without tying the rationale to one chip-generation launch date.
On June 12, 2026, Vertiv completed the acquisition of ThermoKey S.p.A., a leading European provider of heat rejection and heat-exchange technologies. The acquisition expands Vertiv’s thermal management portfolio and manufacturing capabilities in Europe, Middle East, and Africa. CEO Giordano Albertazzi described ThermoKey as expanding options for customers adopting more efficient cooling strategies at scale.
Together these acquisitions broaden Vertiv’s structural, server-side cooling, and heat-rejection capabilities. That is a strategic advantage worth evaluating, not proof that no competitor has comparable coverage. Q2’s acquisition-related growth contribution covers acquisitions as a group; it should not all be attributed to these three deals. PurgeRite, for example, was acquired in December 2025, as the KES announcement confirms.
On September 2, Vertiv agreed to acquire UtilityInnovation Group for approximately $1.45 billion in cash at closing, plus up to $1.15 billion tied to EBITDA targets over 12- and 24-month periods. UIG would add microgrid controls, on-site power orchestration, and behind-the-meter architecture. The announcement expected a Q4 2026 close, subject to approvals and customary conditions; this update does not treat it as completed.
The September 24 KES agreement would add European fluid-management, commissioning, and load-testing services. It also expected a Q4 close; financial terms were undisclosed and not expected to be material. These potential additions broaden the opportunity, but purchase commitments and integration work belong in the investment case too.
Full Year 2026 Guidance: What Management Is Telling You
Following Q2, Vertiv raised full-year 2026 guidance for the second consecutive quarter. The July outlook calls for $13.8 to $14.2 billion in sales, $6.65 to $6.75 in adjusted diluted EPS, and $3.285 to $3.365 billion in adjusted operating profit. The prior Q1 ranges were $13.5 to $14.0 billion in sales and $6.30 to $6.40 in adjusted EPS. These remain forecasts, not reported full-year results.
Two upward revisions are an encouraging sign of management’s confidence. They do not guarantee that every project arrives on schedule or that demand cannot weaken later. The October 28 report will provide the next check on that confidence, including revenue conversion and any change in the full-year outlook.
The July plan puts 2026 capital expenditures at approximately 4.0 percent of revenue. At the $14.0 billion sales-guidance midpoint, that implies roughly $560 million of capex; it is an illustration, not a separately guaranteed cash budget. Capacity investment can support growth, but it also makes execution and cash returns important to monitor.
What the Q2 Reaction Can and Cannot Tell Us
A company can raise guidance and still disappoint investors whose expectations were higher. Stock returns depend on the price paid as well as the business results. This update does not treat an unverified consensus estimate or a precise July price move as a current valuation signal.
A price reaction does not isolate its own cause. Revenue timing, valuation, margins, positioning, and wider market conditions can all matter. This update does not carry the old price-to-book ratio or sector comparison forward as current data. For a fresh valuation, use a dated share price and consistent financial inputs rather than recycling a July multiple.
Management’s timing explanation and the raised annual guide support the constructive case. The next test is whether delayed deployments are completed and cash follows. If later results fall short, the interpretation should change. Investors do not have to choose between ignoring a revenue issue and declaring the entire AI infrastructure thesis broken.
What’s Changed Since Q1: Investment Grade Status and Index Inclusion
Two developments earlier in the year remain useful context. Vertiv’s March 3 financing announcement confirms investment-grade ratings of Baa3 from Moody’s and BBB- from S&P, following February upgrades. It also describes a $2.1 billion unsecured bond offering and a new $2.5 billion revolving facility. That improved financing flexibility; it did not eliminate financial risk.
Vertiv entered the S&P 500 effective March 23, 2026, according to S&P Dow Jones Indices. Index membership can affect passive-fund ownership, but it is not a valuation endorsement or a promise of future buying.
The June 30 cash position provided flexibility, while the subsequent UIG agreement introduces a potentially substantial use of that cash. Keep both facts in view. A strong balance sheet before a transaction does not tell you what leverage, liquidity, or returns will look like afterward.
How Vertiv Fits Into the AI Infrastructure Stack
Understanding where Vertiv sits relative to other AI infrastructure companies helps clarify the investment thesis.
Nvidia (NVDA) and Broadcom (AVGO) design the chips that perform the AI computation. Arista Networks (ANET) builds the networking fabric that connects those chips at scale. Vertiv supplies power-delivery and thermal-management systems that support those chips, alongside other vendors serving the same essential categories.
These companies occupy different, sometimes overlapping layers of the infrastructure stack. Facilities need usable power and cooling before compute can run reliably, but procurement schedules vary and Vertiv is not necessarily the first order placed on every project. Physical infrastructure can provide a long planning horizon while still facing cancellations, delays, changing specifications, and competition.
For our full analysis of the AI infrastructure theme and how these companies interact within the build-out, see our guide to best AI infrastructure stocks to watch in 2026 and our best AI stocks pillar.
The Risk Case
The Q2 report itself is the clearest illustration of the primary risk: revenue timing volatility. Large, multi-phased infrastructure projects do not always land revenue in the exact quarter analysts model, and that mismatch can produce sharp stock reactions even when the underlying demand environment is intact. Investors need to be prepared for this pattern to repeat in future quarters as deployments continue to scale in size and complexity.
Component supply and project execution are the second risk. Management explicitly cited supply-chain congestion in Q2. Large installations also require coordination across utilities, contractors, equipment suppliers, and customers. Delays can affect sales timing, costs, and working capital even when the longer-term demand case remains attractive.
Valuation is the third consideration. A successful infrastructure supplier can still be a poor investment at a price that assumes uninterrupted growth. Use consistent earnings and cash-flow assumptions, test a slower-growth case, and do not treat a decline from a previous share price as proof of a bargain. Proposed acquisitions add integration and capital-allocation risk to that calculation.
Wall Street Reality Check
Q2 gave investors encouraging earnings, margins, and cash-flow figures alongside revenue-timing questions. All of those deserve attention. The raised guide supports management’s confidence, but it does not certify future results or explain every tick of the share price. Read the operating results, the cash-flow statement, and the risk discussion together. The headline is not the whole report, even when it is the one shouting the loudest.
Who Should Own Vertiv
Vertiv may suit investors seeking exposure to the physical power-and-cooling side of the AI build-out rather than only chip designers. That changes the business mix, but it does not make the position defensive: customer capital spending, project timing, competition, and valuation remain important risks.
Growth investors willing to follow the AI capital-spending cycle can use the Q2 results and subsequent deal announcements as a starting point for research. Position size should reflect the possibility that project timing, margins, or acquisition returns disappoint. Conviction is useful; room for being wrong is useful too.
Value-oriented investors should compare the current price with realistic earnings, reinvestment needs, and cash-flow scenarios. A physical-infrastructure label does not automatically make Vertiv cheaper than a semiconductor company, and this article does not establish that today’s shares are a bargain.
For a separate discussion of paid research, our Hidden Alpha review covers the service’s accounting approach and subscription considerations. It is optional reading, not evidence that Vertiv is undervalued or that a proprietary methodology will outperform. Start with the company’s filings and reconciliations; they are available without a newsletter subscription.
Bottom Line
Vertiv’s latest reported quarter showed strong adjusted earnings growth, margin expansion, and cash generation. The September agreements broaden the power-and-cooling strategy while adding transaction and integration questions. The business remains worth following, and October 28 is the next scheduled financial checkpoint. Keep the growth thesis, the price you pay, and the cash needed to deliver it in the same conversation.
Further Reading
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice. StockHitter.com and Jenna Lofton are not registered investment advisors. All investing involves risk, including the potential loss of principal. Past performance does not guarantee future results. Always conduct your own due diligence and consult a licensed financial professional before making investment decisions. Jenna Lofton holds a position in PLTR. Some links on this page may be affiliate links, meaning StockHitter.com may receive compensation if you subscribe to a service at no additional cost to you. This does not influence our editorial opinions.