Originally published: August 1, 2026 | Updated: October 10, 2026 | By Jenna Lofton, StockHitter.com
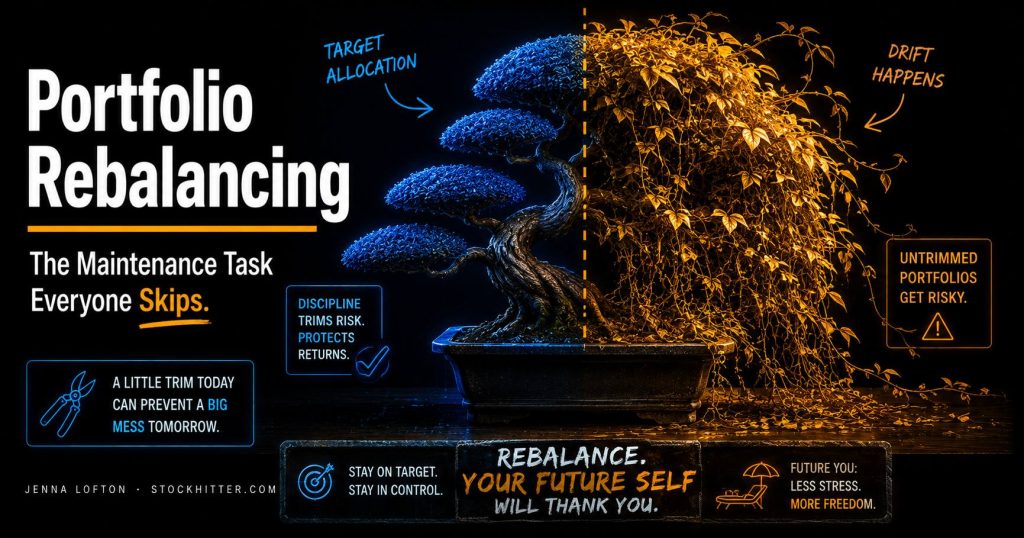
Jenna’s Bottom Line
Quick gut check: when’s the last time you actually looked at your portfolio’s real allocation, not just the account balance? If the answer is “a while,” there’s a decent chance your carefully chosen 60/40 has quietly become something closer to 70/30 without you doing a single thing.
When stocks and bonds grow at different rates, your allocation changes with them. A quick check can show whether you’re still taking the risk you intended.
Key Takeaways
- A portfolio can drift away from its original allocation without a single trade. Bull markets can quietly increase your stock exposure.
- Calendar, threshold, and hybrid approaches all have trade-offs. A five-percentage-point drift is one practical trigger, rather than a universal optimum.
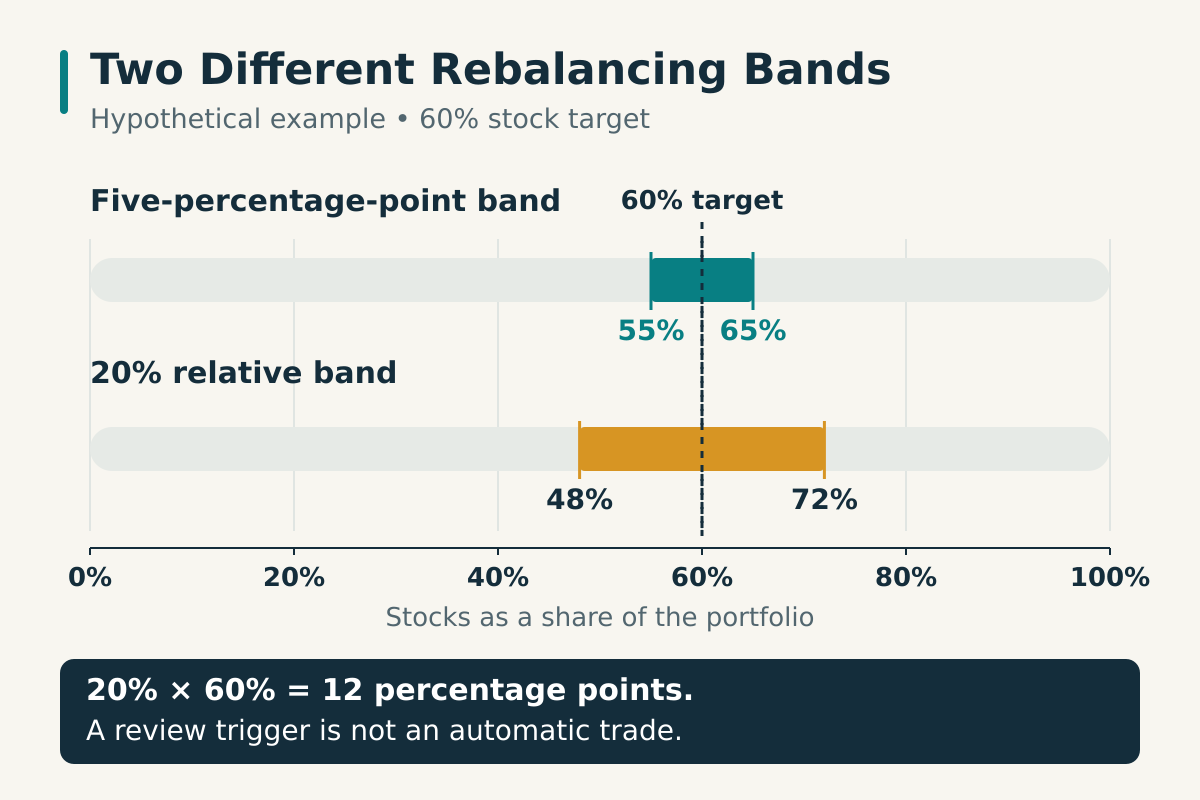
- A relative threshold differs from a percentage-point threshold. At a 60 percent stock target, a 20 percent relative band spans 48 to 72 percent; a five-point band spans 55 to 65 percent.
- Vanguard favors annual rebalancing for many investors. Checking quarterly does not require trading quarterly, and more frequent trading can add costs.
- Taxes still matter. Check holding periods, tax lots, and account type before selling, and consider using new cash to rebalance.
The Portfolio That Quietly Became a Different Portfolio
Here’s a hypothetical example. Start with $60,000 in stocks and $40,000 in bonds: a 60/40 allocation.
If the stocks rise to $90,000 while the bonds remain at $40,000, the portfolio is now worth $130,000. Stocks account for about 69 percent of the total. No trade was needed for the risk exposure to change.
That’s the case for checking your allocation. The account balance alone doesn’t tell you whether the portfolio still matches your plan.
Threshold vs. Calendar vs. the Hybrid Everyone Actually Uses
There are three main approaches to rebalancing. Each balances convenience, allocation drift, and trading costs differently.
- Calendar-based: rebalance on a fixed schedule, quarterly or annually, regardless of how far anything has drifted. Simple to remember. Sometimes rebalances when nothing actually needs fixing, and sometimes misses a fast, ugly drift that happened between scheduled check-ins.
- Threshold-based: rebalance only when an asset class drifts beyond a set percentage, commonly 5 points. It requires regular monitoring or alerts; the frequency determines how quickly you notice a breach.
- Hybrid: check on a calendar schedule, quarterly or annually, but only actually trade if something has crossed the threshold. This separates the decision to review from the decision to trade.
Research does not identify one rebalancing rule that wins for every investor. Vanguard’s investor guidance says an annual rebalance is optimal for many investors after considering risk and trading costs. A quarterly review with a preset drift threshold is another practical approach. Choose a policy that fits your account, costs, and tolerance for drift.
The 5 Percent Rule (And When to Break It)
A five-percentage-point band is one practical starting point. Around a 60 percent stock target, that band runs from 55 to 65 percent. An allocation of 63 percent remains inside the band; 68 percent is outside it.
A 20 percent relative band is different: 20 percent of a 60 percent target is 12 percentage points, so the band runs from 48 to 72 percent. Write down which rule you mean before putting it into practice. Smaller positions may need tighter percentage-point limits.
Daryanani’s 2008 research explored checking portfolios frequently while trading only when allocations moved substantially out of balance. Its findings depend on the assets, thresholds, and market periods studied. They do not establish a guaranteed annual return bonus.
The threshold should reflect the risk you can tolerate and the costs of trading. Pick a rule you can follow, then review it when your goals or circumstances change.
How Often Should You Actually Check?
More frequent trading can increase costs and realize taxable gains without a corresponding improvement in the outcome. Vanguard favors annual rebalancing for many investors. Checking quarterly does not require trading quarterly.
That’s a useful distinction if you’ve ever stared at a red portfolio balance at 11pm for no productive reason.
My practical approach here: review quarterly and consider trading when an allocation crosses its chosen threshold. An annual schedule is another reasonable option. In either case, check taxes and transaction costs before acting.
What This Looks Like With an AI Infrastructure Satellite
Rebalancing gets more interesting once your portfolio includes a satellite of individual high-conviction stocks, which is exactly the structure we recommend in our core and satellite framework.
A stock like Nvidia (NVDA), which has compounded aggressively over the past several years, can grow from a modest 3 percent satellite position into 10 or 12 percent of your total portfolio without you adding a single dollar. That’s not a problem if it’s intentional. It’s a real problem if it just happened while you weren’t looking.
The same threshold logic applies at the position level, not just the asset class level. If a single satellite holding grows beyond the conviction-sized allocation you originally intended, trimming it back isn’t a vote against the business. It’s portfolio hygiene. For our full framework on how large any single position should get in the first place, see our guide to position sizing.
For help distinguishing an allocation trim from a changed investment thesis, see our guide to when to sell a stock.
Experience Transparency
I did not rebalance a single time during the 2021 run-up, and by early 2022 my equity allocation had drifted well past where I meant it to be.
I told myself I was just letting winners run. What I was actually doing was accumulating risk I never consciously chose to take on.
When the 2022 correction hit, that extra drift meant a deeper drawdown than my original plan called for. Nothing catastrophic, but a completely avoidable lesson.
I now set a calendar reminder every quarter specifically to check drift, not to trade by default. Most quarters I do nothing. That’s the system working, not the system failing.
The Tax Question Everyone Overthinks
Rebalancing a taxable account can realize capital gains, so review the tax lots and holding periods before selling. IRS guidance explains that most net long-term capital gains on ordinary stock investments face federal rates of 0, 15, or 20 percent, depending on taxable income and filing status. Short-term gains generally face ordinary income tax rates. The 2026 income thresholds are adjusted for inflation.
An additional 3.8 percent net investment income tax and state taxes may apply. The 2025 tax law did not make future tax policy certain. Plan using current rules and your own tax situation.
New contributions and cash distributions can help fill underweight allocations without selling. Trades inside an IRA or 401(k) generally do not create a current capital-gains bill, although withdrawals have separate tax rules. Consider those accounts first when the available investments fit your overall allocation.
Wall Street Reality Check
Robo-advisors and full-service wealth managers love to market rebalancing as a premium, sophisticated service worth paying an ongoing fee for. It’s genuinely useful. It is also not complicated enough to justify most of what people pay for it.
A workable policy can be simple: check on a schedule, use a threshold suited to your risk tolerance, and consider taxes and trading costs before acting.
Most brokerages let you view your actual allocation percentages for free in about ten seconds. The math is not the hard part. The discipline to actually do it on schedule is the hard part, and no advisory fee fixes that for you if you’re not going to look at the dashboard either way.
A Simple Rebalancing Checklist
Here’s the entire process, reduced to something you can actually follow without a finance degree:
- Set a calendar reminder for once per quarter. Not to trade. To check.
- Pull your real allocation percentages from your brokerage, not your gut feeling about them.
- Compare against your target. Use the band you chose; for a five-point band, a 60 percent target has limits of 55 and 65 percent.
- If an allocation crosses its band, consider new cash first, then tax-aware trades to move back toward target.
- Do it inside tax-advantaged accounts first if you have the option, to avoid triggering unnecessary capital gains.
That’s it. Five steps, once a quarter, and most quarters you’ll do nothing at all. For the broader picture on how this fits into building a portfolio from scratch, see our pillar guide to how to build an investment portfolio.
Bottom Line
Rebalancing is not exciting, and it does not need to be. Different growth rates can move a portfolio far from its starting allocation. Checking that drift helps keep risk aligned with your plan.
Choose a review schedule and a clear rebalancing rule. Consider taxes and costs before trading, and use new cash or tax-advantaged accounts where appropriate.
The whole system takes ten minutes a quarter and most of those quarters, you’ll do nothing. That’s not the system failing. That’s the system working exactly as designed.
Further Reading
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice. StockHitter.com and Jenna Lofton are not registered investment advisors. All investing involves risk, including the potential loss of principal. Past performance does not guarantee future results. Always conduct your own due diligence and consult a licensed financial professional before making investment decisions. Jenna Lofton holds positions in PLTR and NBIS. Some links on this page may be affiliate links, meaning StockHitter.com may receive compensation if you subscribe to a service at no additional cost to you. This does not influence our editorial opinions.