Originally published: August 1, 2026 | Updated: October 10, 2026 | By Jenna Lofton, StockHitter.com
Jenna’s Bottom Line
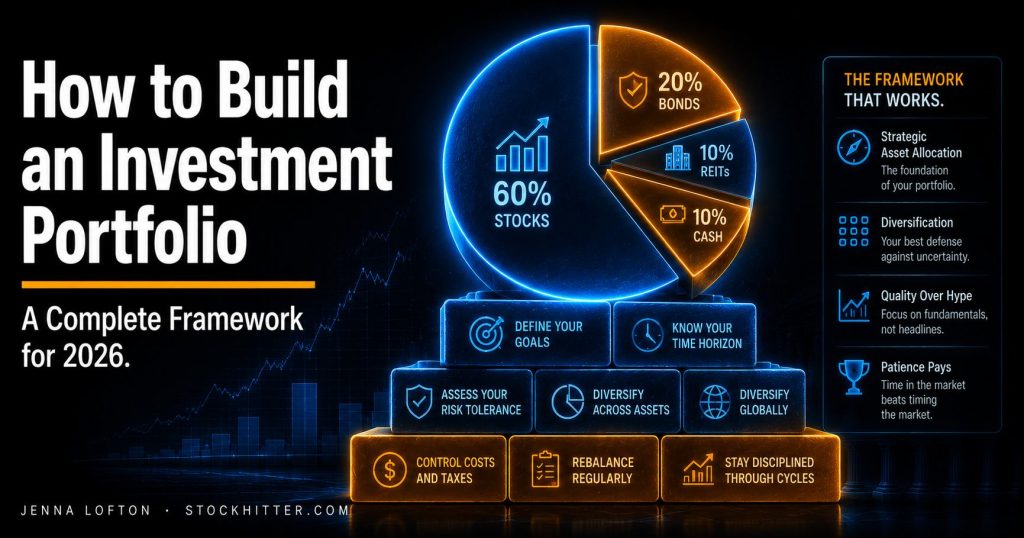
Nobody has ever bragged at a party about their asset allocation, and honestly that’s the whole problem. Vanguard’s 2026 time-varying model put renewed attention on a 40/60 stock-to-bond mix. Its own explanation says that model is a signal about relative risk and reward, not a reason for everyone to overhaul their portfolio. The useful question is whether your allocation still fits your goals.
Key Takeaways
- Vanguard’s 40/60 model is one valuation-aware, time-varying allocation. It is not a blanket replacement for 60/40 or a recommendation for every investor.
- Diversification had a strong year in 2025. Morningstar’s diversified test portfolio beat its U.S. 60/40 benchmark by 5 percentage points. Its research also shows why a single year’s winner need not win over longer periods.
- The core and satellite framework combines a low-cost, broadly diversified core (70 to 80 percent of the portfolio) with a smaller satellite of high-conviction individual positions (20 to 30 percent).
- Structure beats stock-picking swagger for most investors’ long-term returns. Your mix of assets shapes the portfolio’s risk and the way its returns vary over time.
- Your time horizon and risk tolerance, not a one-size-fits-all rule copied from a finance influencer, should determine your specific allocation.
Why Portfolio Structure Beats Stock Picking (Sorry)
Most new investors spend nearly all their time researching which stocks to buy. They spend roughly zero time thinking about how those positions actually fit together as a whole system.
That’s backwards. It’s the financial equivalent of obsessing over throw pillows while your house has no foundation.
Decades of research consistently show that asset allocation, not individual security selection, explains the majority of a portfolio’s return variability over time.
A portfolio isn’t just a collection of good ideas you liked enough to buy. It’s a system with a specific risk profile and a specific ability to survive the years when markets don’t cooperate.
Two investors who each own genuinely excellent individual stocks can end up with wildly different outcomes. The difference usually comes down to whether one of them bothered to build an actual structure.
The Classic 60/40 Portfolio, and What Vanguard’s Model Actually Says
The 60/40 portfolio, 60 percent equities and 40 percent bonds, has been the default recommendation for moderate-risk investors for decades. It’s the financial equivalent of a little black dress: reliable, unremarkable, and somehow still everyone’s answer to “what should I wear to this.”
The logic is straightforward. Stocks provide growth, bonds provide stability and income, and high-quality bonds can cushion equity losses. Their relationship changes over time, and both can decline together.
That relationship broke down badly in 2022, when both stocks and bonds suffered losses.
Rising interest rates pushed both stocks and bonds down at the same time, eliminating the exact diversification benefit investors were counting on precisely when they needed it most. Rude.
Vanguard’s 40/60 example came from its valuation-aware, time-varying approach to portfolio construction. In its February 10, 2026 explanation, chief economist Joe Davis said the model could help investors think about their next investment dollar without making drastic changes to their allocation.
Vanguard’s July 22 update continued to favor bonds relative to its benchmark while distinguishing between unconstrained and constrained model portfolios. Those allocations can change as forecasts change. They are model outputs, not promised returns or a universal retirement formula.
Use your time horizon, spending needs, and ability to withstand losses to set your own allocation. A published model can inform that conversation without deciding it for you.
Beyond 60/40: What Real Diversification Looks Like in 2026
The debate isn’t purely about the ratio between stocks and bonds anymore. It’s increasingly about whether two asset classes were ever enough diversification in the first place, or whether we’ve all just been dividing a pizza into two extremely large slices and calling it variety.
Morningstar’s research offers a useful data point, with an important asterisk. Its April 14, 2026 analysis reported that a diversified test portfolio returned 18.3 percent in 2025, compared with 13.3 percent for a portfolio of 60 percent U.S. stocks and 40 percent U.S. investment-grade bonds. That five-percentage-point advantage was its strongest diversification result since 2009.
Here’s the asterisk: the same research found that the basic 60/40 had stronger returns and risk-adjusted results over the trailing 20-year period ending in 2025. One strong year does not settle the allocation question.
Morningstar’s May 27 discussion emphasized that U.S. stocks, international stocks, investment-grade bonds, and cash can meet most investors’ needs. Additional asset classes are optional. It also noted that high-quality bonds had resumed their diversification role by the end of 2025 after the disruption in 2022.
The 2025 diversification win reflected a particular environment, including strong international equities and gold. This year’s winning outfit doesn’t necessarily win every year.
The Core and Satellite Framework (Or: How I Learned to Stop Panicking and Structure My Portfolio)
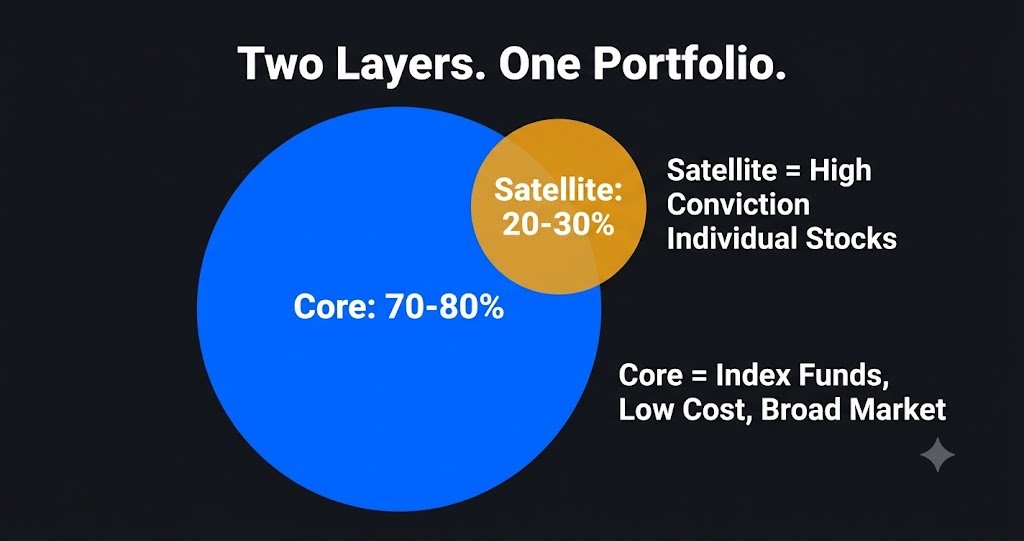
For investors who want individual stock positions alongside diversified funds, one way to apply this is the core and satellite structure. The percentages below are an illustration; a smaller satellite, or no satellite, may suit you better.
- The core (70-80% of the portfolio): low-cost, broadly diversified index funds covering the total U.S. market, international developed markets, and a bond allocation sized to your time horizon. This is the boring foundation that reliably captures market returns with almost zero ongoing decision-making.
- The satellite (20-30% of the portfolio): higher-conviction individual positions where you’ve actually done the research, not just a strong feeling and a group chat. This is where AI infrastructure names like Nvidia (NVDA) or Palantir (PLTR) fit for investors with a genuine thesis and the time horizon to hold through the volatility.
Because the satellite represents a minority of total capital, one bad call doesn’t take the whole portfolio down with it.
This structure also solves a real behavioral problem, not just a spreadsheet problem. When the core is doing its job, you’re participating in broad market returns regardless of how any single satellite position performs.
That removes the pressure to force returns out of your individual picks, which is exactly the moment the worst investment decisions get made. For our full breakdown of this structure applied to individual investing strategies, see our guide to investing strategies.
Building the Fixed Income Side Without Just Buying One Bond Fund and Calling It a Day
The bond portion of a portfolio is not one uniform asset class, and treating it that way is a mistake I see constantly. Treasury bonds, corporate bonds, high-yield bonds, and international bonds all behave differently and serve different jobs within an allocation.
- Treasury bonds: low default risk, but longer maturities can still fall sharply when yields rise. Their diversification benefit depends on the market environment.
- Core investment-grade corporate bonds: higher yield for modest extra risk.
- High-yield bonds: behave more like stocks in disguise, since they carry meaningful default risk. That quietly defeats the point of holding them for stability.
- International bonds: exposure to other issuers and economies, with currency risk to consider when the holdings are unhedged.
A broad bond index fund can already hold a diversified mix of issuers. Check its duration, credit quality, and geographic exposure before deciding whether additional funds fill a useful gap.
Diversification Beyond Stocks and Bonds (Yes, There’s More)
Alternative assets, real estate investment trusts, commodities, and gold among them, offer diversification benefits that neither stocks nor traditional bonds fully replicate on their own.
Gold can behave differently from stocks and bonds, but it can also fall during periods of stress. Its usefulness depends on the time period, portfolio weight, and risks you are trying to manage.
The right allocation to alternatives depends on your circumstances. Adding more holdings does not automatically create better diversification; check their correlations, costs, liquidity, and underlying exposures.
Experience Transparency
I ran a fairly standard 80/20 stock-to-bond allocation heading into 2022. The simultaneous decline in both asset classes taught me something I had read about academically a thousand times but never actually felt in my gut before. Diversification only works when the assets you’re holding actually behave differently from each other, and in 2022 they did not get that memo. I rebuilt my defensive allocation afterward to include a genuine mix of Treasuries, shorter-duration bonds, and a small gold position, specifically because I wanted assets that would respond differently to a rate-driven selloff. The structure held up dramatically better through the 2023 volatility that followed.
Matching Your Portfolio to Your Time Horizon
There’s no single correct allocation, no matter how confidently someone on the internet presents one. The right structure depends entirely on how long your capital needs to stay invested before you actually need to touch it.
- 20+ years until retirement: generally afford higher equity exposure, since there’s time to recover from multi-year drawdowns. A 90/10 or 80/20 stock-to-bond split has historically been appropriate here.
- 5 to 15 years from retirement: review the balance between growth, income, and capital preservation as planned withdrawals get closer. Your spending needs and other income sources matter alongside the retirement date.
- Within 5 years of needing the capital: prioritize capital preservation heavily, with a meaningfully larger allocation to bonds and cash equivalents, regardless of what the market is doing that week.
For a complete breakdown of positioning across a full market cycle, see our guide to market cycles explained.
Rebalancing: The Discipline Everyone Conveniently Forgets Exists
A portfolio built with the right allocation on day one will not stay that way. Different assets grow at different rates, and your portfolio does not care about your intentions.
Rebalancing means periodically selling positions that have grown beyond their target weight and buying positions that have fallen below it, restoring the risk profile you actually meant to have.
This discipline forces a systematically contrarian behavior: selling what’s recently performed well and buying what’s recently underperformed. That’s emotionally uncomfortable and mechanically sound, which is precisely why most people never actually do it. For our complete framework, see our guide to portfolio rebalancing.
Position Sizing Within the Satellite
Building the satellite portion of a portfolio requires its own discipline around how much capital any single conviction position actually deserves.
A satellite holding sized too aggressively defeats the entire purpose of the core and satellite structure. A single position’s failure can then meaningfully damage the whole portfolio, the exact outcome this structure was supposed to prevent.
For a complete framework on position size, see our guide to position sizing. For knowing when a satellite position’s thesis has actually changed enough to warrant an exit, see our guide to when to sell a stock.
For investors who want a structured research framework built around long-term, fundamentals-first portfolio construction, Stansberry Investment Advisory offers position sizing and risk management discipline that pairs naturally with the core and satellite structure described here.
Wall Street Reality Check
The financial industry has promoted the 60/40 portfolio for decades partly because it’s simple, easy to explain in a single sentence, and easy to sell as a packaged product. Vanguard’s time-varying model shows how valuation assumptions can change a model allocation. A long-term investor still needs a durable policy that fits their own goals, spending needs, and risk tolerance. Review that policy when circumstances change rather than chasing every new forecast. Rules of thumb are a starting point. They are not a personality.
Bottom Line
Building a portfolio well means starting with structure, not stock picks, no matter how tempting the stock picks are. Decide your core allocation based on your genuine time horizon and risk tolerance, not a rule you memorized off a finance meme. Build a satellite of high-conviction positions sized appropriately within that structure. Rebalance on a disciplined schedule instead of whenever you happen to remember. The specific numbers Vanguard, Morningstar, or anyone else recommends today will change again as conditions evolve. The discipline of thinking through structure first will not.
Further Reading
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice. StockHitter.com and Jenna Lofton are not registered investment advisors. All investing involves risk, including the potential loss of principal. Past performance does not guarantee future results. Always conduct your own due diligence and consult a licensed financial professional before making investment decisions. Jenna Lofton holds positions in PLTR and NBIS. Some links on this page may be affiliate links, meaning StockHitter.com may receive compensation if you subscribe to a service at no additional cost to you. This does not influence our editorial opinions.