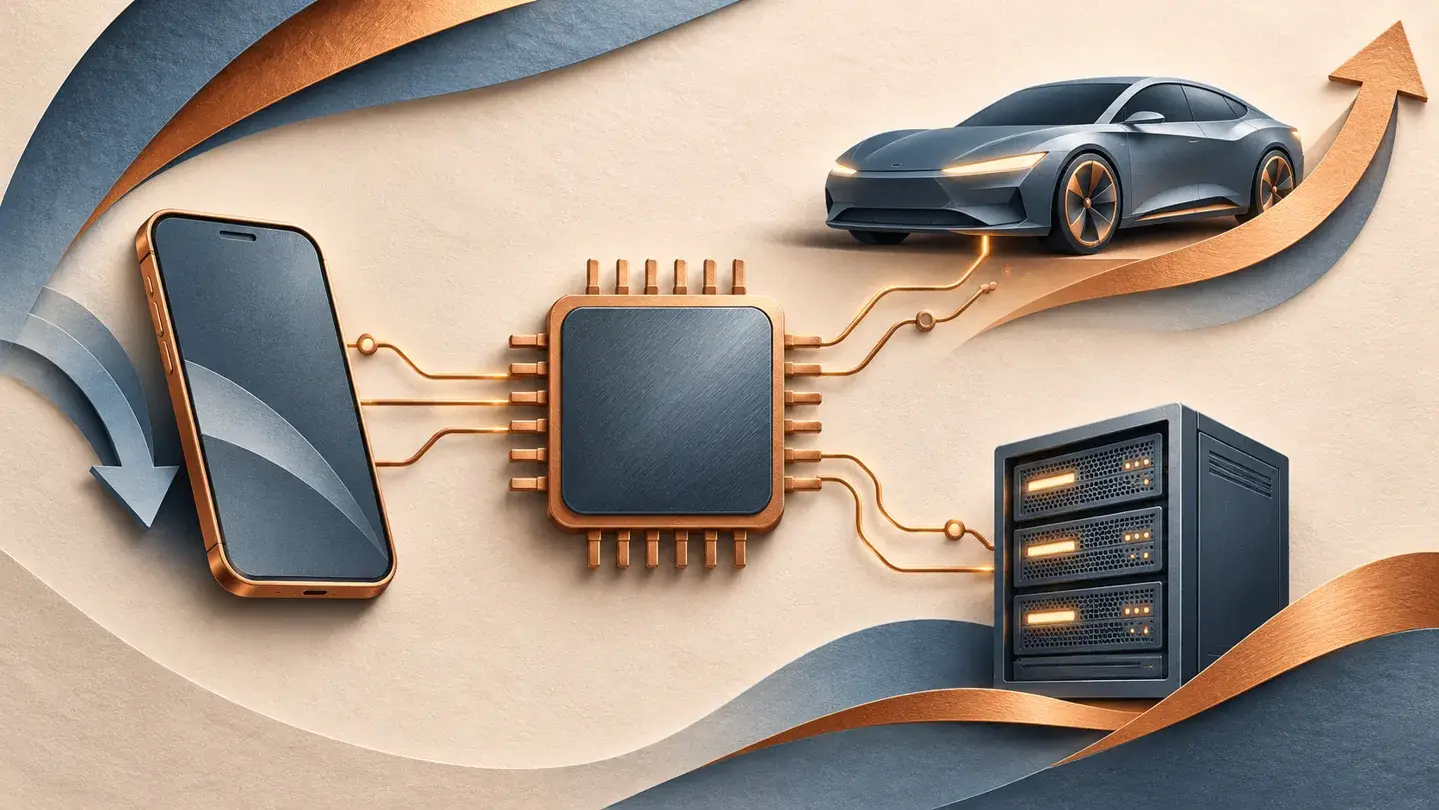
Qualcomm’s automotive business is growing quickly, but it hasn’t grown large enough to cover the hole left by weaker phone-chip sales. That’s the useful starting point for its latest results: a genuine diversification story, with some fairly demanding arithmetic still attached.
For its fiscal fourth quarter ended September 27, Qualcomm reported $10.322 billion in GAAP revenue, down 8% from a year earlier. Adjusted earnings fell 28% to $2.17 a share. The company’s November 4 earnings release also outlined substantial growth ambitions for fiscal 2027. Investors have two different things to weigh here: what the business earned and what management expects its newer businesses to deliver.
The phone-chip decline is still the bigger number
Quarterly handset revenue fell 26% to $5.137 billion. Automotive revenue jumped 89% to $1.990 billion, while Internet of Things revenue increased 4% to $1.888 billion.
The percentages make cars look like the obvious star, and the growth is meaningful. But a smaller business can post a spectacular growth rate without replacing a larger business’s lost sales. Compared with the same quarter a year earlier, handsets lost $1.824 billion in revenue. Automotive and IoT together added $1.018 billion, covering about 56% of that decline.
That leaves diversification doing useful work without yet solving the immediate sales problem. Qualcomm’s QCT chip segment reported a 24% pretax earnings margin, down from 29%. That’s a five-percentage-point decline, another reason revenue growth in a newer category doesn’t automatically translate into stronger companywide earnings.
There’s also a timing issue. Qualcomm says higher costs across manufacturing, testing, packaging and materials have prompted price increases. It expects the full gross-margin benefit from those pricing actions in the second half of fiscal 2027. The timing matters: the full benefit remains a management forecast for a later period.
A big annual profit jump needs a tax explanation
Full-year GAAP earnings rose to $12.70 a share from $5.01. Read in isolation, that looks like a very different company from the one reporting weaker quarterly sales.
The bridge is a $5.7 billion tax benefit recorded in fiscal Q2. Qualcomm reversed an allowance against federal deferred tax assets that it had established in the fourth quarter of fiscal 2025. Last year’s GAAP result carried the expense; this year’s result includes the reversal. That makes the annual comparison a poor shortcut for judging operating momentum.
Adjusted annual earnings moved in the opposite direction, falling 12% to $10.54 a share. Those figures need their own context: Qualcomm’s adjustments remove costs including share-based compensation and acquisition-related items. Some excluded costs recur. Our guide to reading an earnings report explains why comparing the measures is more useful than automatically crowning either one the “real” profit.
The data-center opportunity comes with a new scoreboard
Management projects more than 60% growth in non-handset revenue in fiscal 2027 and reiterated a $5 billion Data Center revenue target for that year. Qualcomm also announced a multigenerational AI data-center product collaboration with Amazon. The release doesn’t put a dollar value on that collaboration, so treating it as a guaranteed contribution toward the target would run ahead of the disclosure.
These are potentially important additions to the business. They’re still forecasts and announced plans, rather than $5 billion of revenue already earned.
For fiscal Q1 2027, Qualcomm forecasts total revenue of $10.4 billion to $11.2 billion and adjusted earnings of $2.15 to $2.35 a share. One small footnote deserves a large mental bookmark: the QCT revenue outlook includes Data Center. Comparing that forecast with the historical chip segment without acknowledging the added business would muddy the picture.
Licensing provides another counterweight. Qualcomm announced long-term patent-license renewals with Apple, Huawei and Transsion, and its licensing segment’s full-year revenue was approximately flat. Those renewals are useful evidence of continuity in licensing. They aren’t a promise that those customers will buy more Qualcomm chips.
Watch the cash alongside the growth targets
Fiscal 2026 operating cash flow was $11.145 billion, down from $14.012 billion, while capital spending rose to $2.494 billion from $1.192 billion. Subtracting capital spending gives a simple free-cash-flow calculation of $8.651 billion, versus $12.820 billion a year earlier. That calculation isn’t a guarantee that all the cash is available for shareholder payouts.
Qualcomm has real growth outside phones, a substantial licensing business and positive cash generation. The next useful test is whether new revenue starts closing the handset gap while chip margins improve. Keeping those measures beside the ambitious fiscal 2027 targets gives investors a clearer view than either the automotive growth rate or the tax-assisted annual profit headline alone.