NXP’s New Chip Factory Is Open. Now It Has to Earn Its Keep.
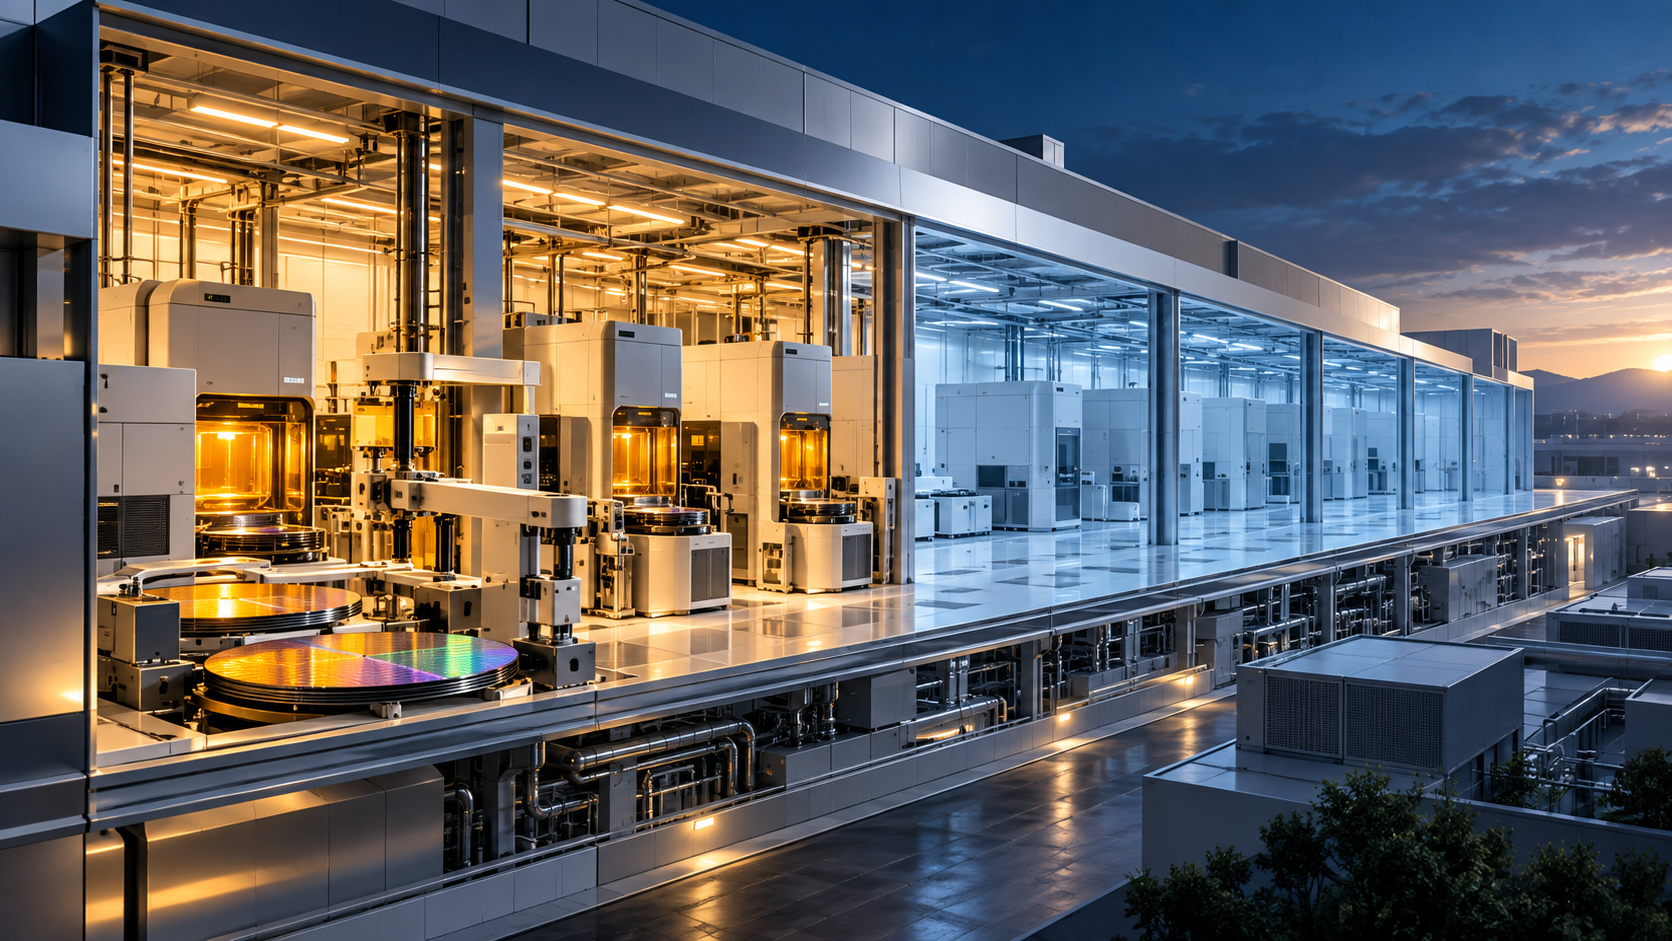
A chip factory can have an opening ceremony months before it starts volume production. The ribbon gets cut on schedule. The economics take a little longer.
On September 28, NXP Semiconductors and Vanguard International Semiconductor’s joint venture, VSMC, opened its first 300mm wafer factory in Singapore. Construction is complete, but the company’s announcement puts volume production in the first quarter of 2027. The plant is currently in the risk-production stage, the trial phase before that ramp.
For shareholders, that gap deserves attention. A finished building removes one set of uncertainties. Getting it to produce consistently, serve customers and earn an attractive return is the work that follows.
What actually opened
The Tampines facility is a specialty-chip plant, supporting technologies used in power management, analog and mixed-signal products, among other applications. Its customers’ end markets include automotive, industrial, mobile and high-performance computing.
The Straits Times reported the opening and described how specialty semiconductors help manage power and control systems. Those jobs can matter considerably even when the components don’t get their own breathless keynote.
I like this as a reminder to look beyond the best-known processor brands when following semiconductor investment. Different chips solve different problems, and the businesses making them can face very different demand and pricing conditions.
One number has changed since the original plan
Monday’s release targets approximately 44,000 wafers per month at full capacity in 2029. A wafer is the round substrate on which chips are manufactured; a wafer count isn’t a count of individual chips.
Go back to the original June 2024 announcement and the expectation was 55,000 wafers a month in 2029. The latest figure is 11,000 lower, a 20% difference.
There’s a qualification worth keeping beside that calculation: NXP says its own planned manufacturing capacity at VSMC remains unchanged. The two statements leave a question about the overall project’s capacity assumptions. They don’t support declaring that NXP cut its allocation by 20%.
The current release doesn’t explain the difference between those project-level targets. I’d want that explanation before treating the lower number as evidence of weaker demand, worse economics or a problem with construction. Product mix and the scope of a capacity measure can matter; we shouldn’t invent an explanation on the company’s behalf.
Why filling the factory matters
A factory has costs that don’t politely disappear when fewer orders arrive. Buildings, equipment and a core operating team still have to be supported.
Here’s a deliberately simplified hypothetical, unrelated to VSMC’s reported costs or forecasts. Suppose a plant carries $30 million in monthly fixed manufacturing costs. At 40,000 wafers a month, those costs average $750 per wafer. At 30,000 wafers, the average rises to $1,000.
Output fell 25%, but fixed cost per wafer rose about 33%. That’s the arithmetic behind why utilization, meaning how much available capacity is being used, attracts so much attention.
This isn’t a complete cost estimate. Materials, energy and other variable expenses sit outside the example. The number of usable chips from each wafer, selling prices, product mix and accounting treatment also affect the result. Some costs can change as production changes. Holding one cost bucket steady simply makes the relationship visible.
The reverse can help a manufacturer: spreading fixed costs across more output can improve unit economics. Whether that produces better margins depends on what customers pay and what it costs to deliver the additional output.
Give the next earnings call a specific question
If you follow NXP, write down the first-quarter 2027 volume-production target and the latest 2029 capacity expectation. Keep the earlier target beside it, clearly marked as the old plan.
Then look for management’s explanation of the ramp: customer demand, production progress, costs and how the venture affects NXP’s financial results. Our guide to reading an earnings report walks through margins, cash flow and guidance, the places where a manufacturing investment eventually has to show its value.
My view is that completing the facility is meaningful progress. I’d give the subsequent production and financial disclosures more weight than the opening-day photographs, however impressive the machinery looks. A factory investment earns its place in an investment case over several reporting periods.
The useful question now is how smoothly this facility moves from a completed project into a productive part of the business, and what that contribution costs NXP along the way.
Educational analysis, not personalized investment advice. Investing involves the risk of loss.
Affiliate disclosure: StockHitter may earn a commission if you subscribe through the offer link below, at no additional cost to you.
Give your stock research a regular starting point
Want help finding ideas to investigate between earnings reports? Power Gauge Report is Chaikin Analytics’ paid investment research service, offering monthly recommendations, a model portfolio and stock ratings. It can give you a shortlist to research instead of starting from a blank screen. The ratings can be wrong, and they don’t replace checking a company’s finances.
See what Power Gauge Report includes →
Want the details before looking at the offer? Read my full Power Gauge Report review.
