How do you check whether a stock is being diluted?
To check stock dilution, start with shares actually outstanding, reconcile what changed, then read the earnings-per-share and equity-compensation notes. Each answers a different question. We’ll keep them separate so you don’t spend an afternoon trying to reconcile numbers that were never meant to match.
A company can announce a giant buyback and still issue plenty of new shares. Its basic and diluted earnings per share can match while potential dilution waits in the footnotes. You came here to count shares, and somehow the shares brought paperwork.
First, decide which kind of dilution you’re measuring
The SEC defines dilution as new share issuance that reduces existing shareholders’ percentage ownership. If you keep the same number of shares while the total grows, your slice of ownership gets smaller.
That gives us three useful checks:
- Ownership: How many shares are outstanding on the comparison dates?
- Reported earnings: How many weighted-average shares were used to calculate basic and diluted EPS?
- Future issuance: What awards, options, warrants or convertible securities might create more shares?
Keep separate lines for these. A diluted EPS denominator cannot tell you precisely what percentage of the company you own today. Giving each count its own label saves a surprising amount of spreadsheet grumbling later.
1. Open the filing and label your dates
Search the company in SEC EDGAR. Open its latest 10-K and any more recent 10-Q, then pull the comparable earlier filing. This workflow suits U.S. companies filing those forms; foreign issuers can use different forms.
The annual 10-K contains audited financial statements. Quarterly 10-Q statements are generally unaudited. In the 10-K, Item 8 contains the financial statements and notes, as the SEC’s filing guide explains.
Write down the fiscal period, share class and units before copying numbers. A table labeled “in thousands” needs a multiplication by 1,000. Tiny label, enormous difference. Also record the date beside the cover-page share count. It can be later than the balance-sheet date.
For a trend, compare equivalent dates and periods: year-end with year-end, or this quarter’s weighted average with the same quarter last year. Keep a nine-month average out of a three-month comparison.
2. Build a bridge between the outstanding share counts
Search the filing for “shares outstanding,” “stockholders’ equity,” “shareholders’ equity” and “repurchase.” Find a share-count reconciliation in the equity statement or its notes.
The basic bridge is: beginning shares, plus shares issued, minus shares repurchased or otherwise removed from outstanding shares, equals ending shares. Follow the company’s actual categories. Some issuance figures are already net of shares withheld for employee taxes.
Use outstanding shares for ownership calculations. Authorized shares describe permitted issuance capacity; they aren’t all already in investors’ hands. With multiple share classes, check their economic and voting rights before combining counts.
Then calculate the net change: ending outstanding shares divided by beginning outstanding shares, minus one. A decline can coexist with substantial issuance if buybacks more than offset it. Read both sides of the bridge. Otherwise, you can cheer the departures without checking the arrivals.
A real filing walkthrough: Apple’s fiscal 2024
Open Apple’s 2024 10-K and search for Note 10. This is a historical teaching example, not a current assessment of Apple.
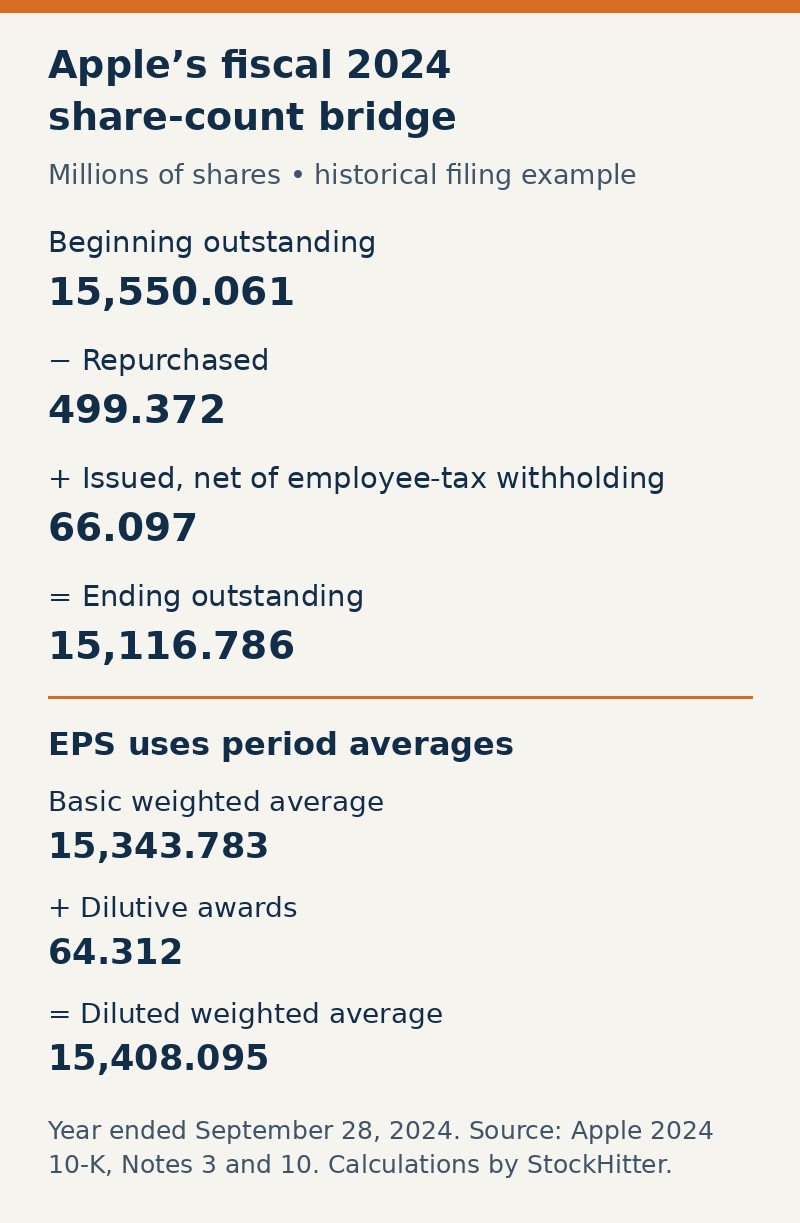
Its reconciliation reports shares in thousands. Converted to millions:
- Start of fiscal year: 15,550.061 million
- Repurchased: 499.372 million
- Issued, after employee-tax share withholding: 66.097 million
- September 28, 2024 ending balance: 15,116.786 million
The arithmetic is 15,550.061 − 499.372 + 66.097 = 15,116.786 million. Outstanding shares fell about 2.79%, although the company issued shares.
Now search for Note 3. Fiscal 2024 weighted-average basic shares were 15,343.783 million. Adding 64.312 million from dilutive share-based awards produced 15,408.095 million weighted-average diluted shares.
That diluted figure is larger than the year-end outstanding balance. If your first reaction is “hang on,” that’s a useful reaction. Both can be correct: one measures an EPS denominator across the year, including specified potential shares; the other counts outstanding shares on one date.
3. Give the EPS denominator its own inspection
Basic EPS uses weighted-average shares for the reporting period. Shares issued halfway through a period affect that average for only the remaining portion. Diluted EPS incorporates potentially dilutive securities under accounting rules, rather than simply adding every possible future share.
For options, the treasury-stock method assumes exercise proceeds are used to buy shares at the period’s average market price. This is a calculation convention, separate from actual corporate buybacks. Convertible instruments generally use the if-converted method, which can also require adjustments to the earnings numerator. FASB’s ASU 2020-06 explains these mechanics.
Look for an antidilutive-securities disclosure, too. During a loss period, including additional shares can make the loss per share appear smaller. Potential shares are excluded from diluted EPS when their effect is antidilutive. Roku’s 2024 10-K, Note 15, illustrates that treatment. Matching basic and diluted EPS therefore doesn’t establish that future dilution is absent. The accounting calculation hasn’t handed the company a “no more shares” certificate.
Compare GAAP figures on the same basis. If management also presents adjusted EPS, read its reconciliation before assuming it uses the identical denominator.
4. Trace where additional shares could come from
Employee compensation: Read the equity-award tables for grants, vesting, exercises, cancellations and remaining awards. Also inspect the stock-compensation expense policy. An expense measured in dollars and a count of shares issued measure different things. Roku’s stock-compensation disclosures in Notes 2 and 11 are useful examples of those separate tables. Dividing compensation expense by today’s stock price won’t reliably reconstruct actual issuance.
Convertible debt and warrants: Search the debt and equity notes for conversion prices, conversion conditions, exercise terms and cash-versus-share settlement. The SEC’s convertible-securities guide highlights an especially important distinction: a fixed conversion formula versus one tied to a changing market price. The latter can require more shares as the price falls.
New financing or acquisitions: Look for stock issued to raise cash or pay for another business. Check subsequent-events disclosures and later 8-Ks for developments after the reporting date. Ask what the company received in return and whether the expected benefit supports the larger share count.
Buybacks: Compare actual shares acquired with actual issuance. A repurchase authorization is permission to spend; its headline dollar amount doesn’t tell you how many shares were ultimately removed. The press release doesn’t retire a single share by looking impressive.
5. Check the ownership math without mixing in EPS
Suppose a hypothetical company has 100 million shares, and you own 10,000. Your stake is 0.01%. It issues 10 million shares to other investors, with no buybacks, splits or changes to your holding.
The new total is 110 million. Your ownership becomes about 0.00909%. The share count rose 10%, while your percentage ownership declined about 9.09% relative to its original level. Those percentages use different denominators.
If issuance happened exactly halfway through the year, the basic weighted-average count would be 105 million, assuming no other changes. At $120 million of income available to common shareholders, basic EPS would be about $1.14. Dividing by the 110 million year-end count would incorrectly give about $1.09 for that year’s basic EPS.
One final check: did the stock split?
A stock split increases shares proportionately without diluting ownership by itself. A two-for-one split doubles both your holding and the company’s share count. Cutting your sandwich into four pieces instead of two doesn’t give somebody else half your lunch. A reverse split combines shares, although fractional holdings may be cashed out. Use consistently split-adjusted figures when comparing periods.
Then bring the share count back into the wider business picture. Our guide to reading an earnings report puts EPS alongside revenue, margins and cash flow.
Finish with three lines: how outstanding shares changed, what caused the change, and what could issue next. You can keep this tidy even when the filing is anything but. Then ask what shareholders received in return for any new issuance. That is the question the headcount alone can’t answer.
For general education. This guide is not personalized investment advice.