Applied Digital’s revenue grew 322%. That certainly gets my attention. Before getting too attached to that number, though, I want to know what the company actually sold.
The answer includes a growing rental business and a much larger amount of work getting customers’ equipment installed. Both produce revenue. They make very different contributions to the business investors are trying to value.
In its October 7 earnings release, Applied Digital reported $341.9 million in revenue for its fiscal first quarter, which ended August 31. The company trades on Nasdaq as APLD.
The biggest revenue line deserves a closer look
Applied Digital’s high-performance computing hosting business generated $262.6 million. That included $183.5 million of tenant fit-out services, $65.8 million of base rent and $13.3 million of tenant recoveries.
Fit-out work accounted for approximately 54% of the company’s total revenue. Its annual filing describes these services as procuring and installing equipment, with costs reimbursed plus a contractual markup.
That’s useful work. It also means a large customer invoice can come with a nearly matching supplier bill.
The new quarterly filing’s segment table puts fit-out revenue at $183.518 million and its service costs at $176.100 million. Subtracting those figures leaves roughly $7.4 million, or a 4.0% gross margin, before segment overhead.
I wouldn’t multiply the entire sales figure by four and call it an annual rental business. Installation work can continue across new projects, but its timing and economics deserve their own assumptions.
The rental growth is real, too
There’s a genuinely encouraging part here. Base rent increased from $44.1 million in the previous quarter to $65.8 million, a sequential increase of approximately 49%.
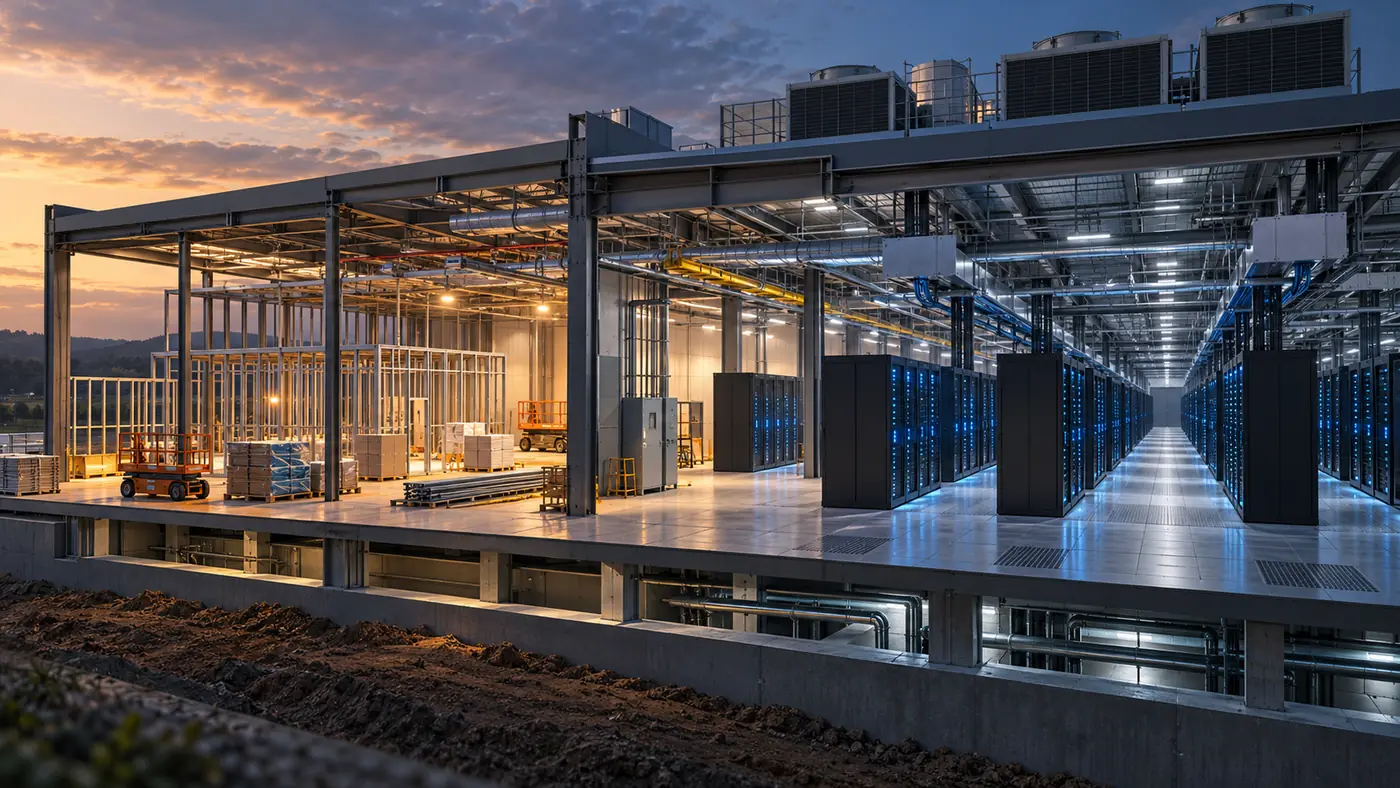
Polaris Forge 1 had 175 megawatts of operating capacity at quarter-end. Another phase brought that to 250 megawatts on October 1, after the reported quarter ended.
That timing matters when reading the next set of results. The October addition contributed no operating capacity during the reported quarter. The current rental figure therefore doesn’t describe a full quarter at today’s capacity.
The company also reported $58.8 million of rental net operating income, a non-GAAP measure with an 89% margin that excludes depreciation, financing costs and corporate overhead.
Still, capacity alone won’t settle the investment case. I’d want to see how the additional rent translates into earnings after the expenses of owning, financing and running those facilities.
One accounting detail is easy to miss: rent is recognized on a straight-line basis under lease accounting. Recognized rental revenue and cash rent collected needn’t match in a particular quarter.
Read the adjusted figures with their boundaries attached
Applied Digital reported a $221.0 million continuing-operations loss attributable to common shareholders, or 76 cents a share. Its adjusted loss was $4.1 million, or 1 cent a share.
That’s a substantial difference, and the reconciliation earns its reading time. Adjusted results exclude ChronoScale, the approximately 96%-owned business that remains consolidated in the GAAP financial statements, along with stock compensation and other specified expenses and valuation changes.
The adjusted measure starts from consolidated continuing-operations net loss, rather than the larger loss attributable to common shareholders. Treating the two headline losses as a simple list of expense add-backs would miss that distinction.
Management’s view of its core business is useful. Shareholders also need the full-company result. That fits the broader approach in our guide to reading an earnings report: check the underlying figures together before deciding what the headline means.
Construction still needs financing
Operating cash flow was positive $63.9 million. Cash purchases of property, equipment and other assets were approximately $2.075 billion.
Working capital also helped operating cash flow, including increases in accrued liabilities and deferred revenue. Cash received ahead of services, or expenses recognized ahead of payment, can affect the quarter’s cash result. I’d check how those balances develop as the projects progress.
The business is building facilities on a scale its current operating cash generation doesn’t cover. That makes funding terms part of the earnings story, rather than something to leave for the back pages.
At August 31, cash, cash equivalents and restricted cash totaled approximately $3.7 billion, including $728 million of restricted cash. Reported debt was approximately $6.4 billion.
Management expects its resources and access to financing to meet requirements for at least the next 12 months. It also warns that additional funding might not be available on acceptable terms. Those two disclosures belong together.
For the next report, my focus would be rental growth, the earnings it leaves behind and the financing needed to deliver more capacity. The 322% headline is impressive. The mix underneath it tells us much more about what shareholders actually own.